Minimum coverage and full coverage offer very different levels of financial protection. Minimum coverage generally refers to the insurance required by your state, while full coverage typically combines liability insurance with comprehensive and collision coverage.
The better choice depends on your vehicle’s value, whether you finance or lease it, your budget, and how much financial risk you can comfortably take on. This guide compares what each option covers, how much they can cost, and when paying for full coverage may be worthwhile.
See the Real Cost Difference
Compare minimum liability and full coverage costs side by side for your specific vehicle.
Minimum coverage is not necessarily the same as liability-only insurance. Minimum coverage refers to the basic level of auto insurance required by your state. In most cases, this includes liability insurance that covers damages you cause to other people or property.
Coverage usually includes:
Bodily injury liability
Property damage liability
Coverage does not include:
Damage to your own vehicle
Theft
Weather damage
Vandalism
Hit-and-run damage
Because it offers limited protection, minimum coverage policies usually cost less than full coverage.
What Is Full Coverage Auto Insurance?
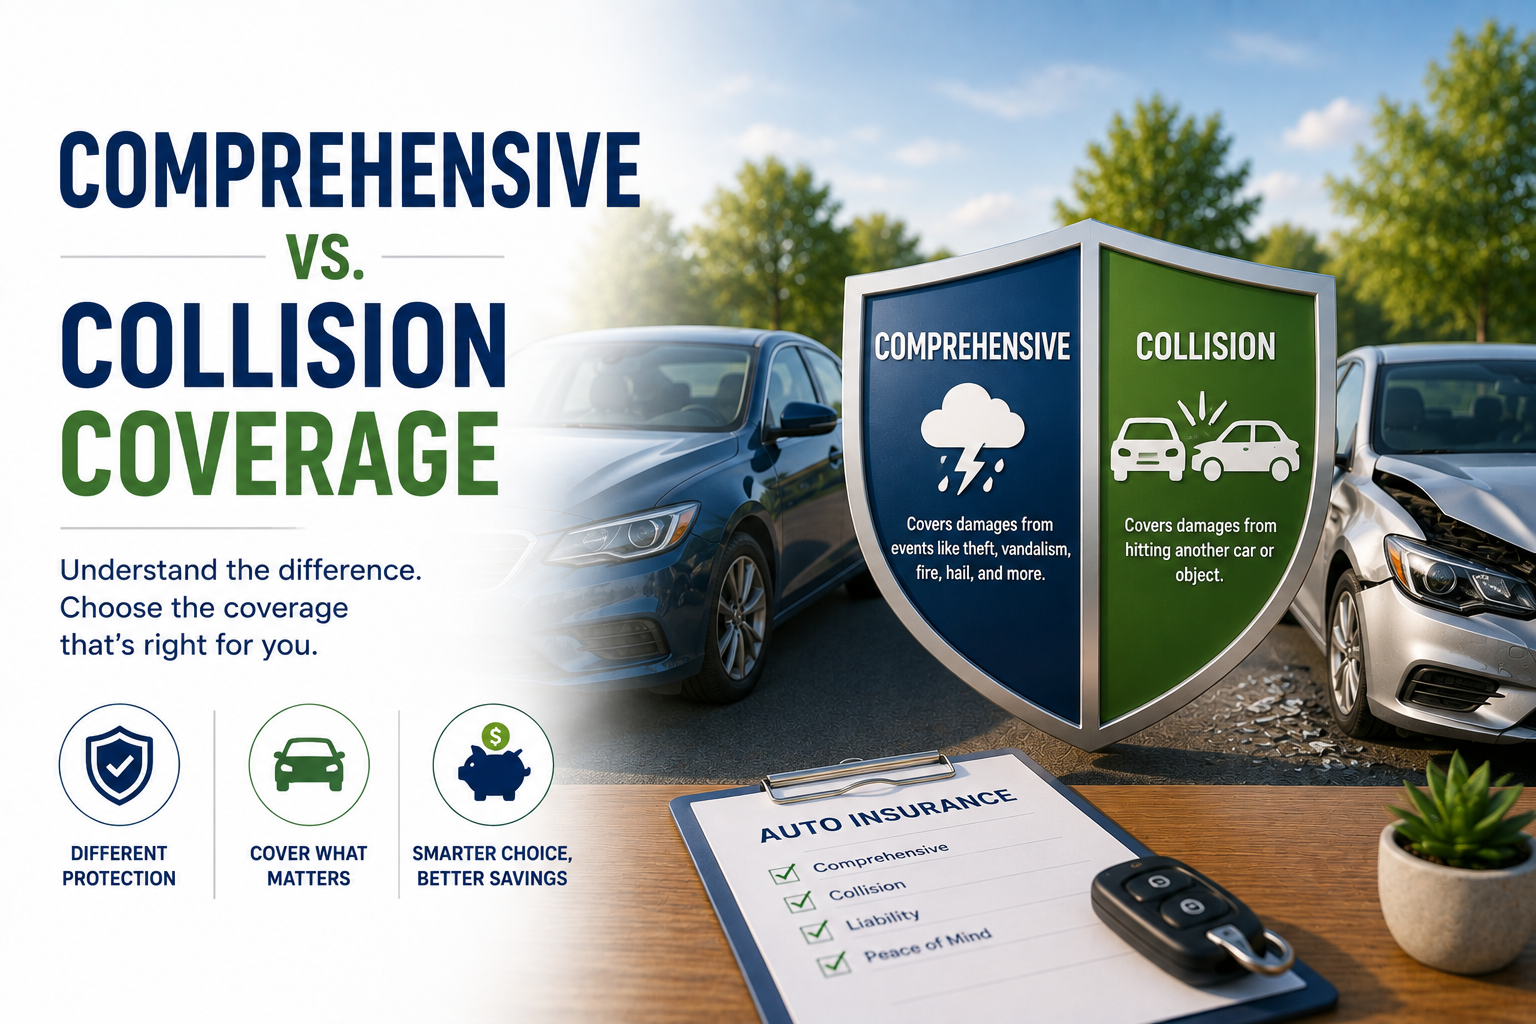
Full coverage is not an official insurance product but rather a common term used to describe a policy that includes liability, collision, and comprehensive coverage.
Full coverage typically includes:
Collision coverage
Liability coverage
Comprehensive coverage
Some drivers also add:
Uninsured motorist coverage
Personal injury protection
Rental reimbursement
Full coverage provides broader protection but costs more because it covers more risks.
Key Differences Between Minimum and Full Coverage
Minimum coverage focuses on meeting state liability requirements, while full coverage generally combines liability with collision and comprehensive protection. The table below shows how the two approaches differ.
Feature
Minimum Coverage
Full Coverage
Meets legal requirements
Covers damage to others
Covers your vehicle
Covers theft
Covers weather damage
Monthly cost
Lower
Higher
Financial protection
Limited
Strong
When Minimum Coverage May Be Enough
Minimum coverage may make sense when:
Your vehicle is older and has low value
You could afford to replace your vehicle
You need the lowest possible premium
Your car’s value is low relative to the annual premium
Some drivers choose minimum coverage when repair costs would exceed the car’s value.
When Full Coverage May Be Worth It
Full coverage may be worth considering if:
Your vehicle is newer
Your car still has significant value
You have a loan or lease (often required)
You want protection against theft or weather damage
You cannot afford major repair costs
Drivers with vehicles worth more than a few thousand dollars often choose full coverage to reduce financial risk.
Table of Contents
Emily Foster
Insurance Policy Analyst
Emily Foster writes insurance comparison content at InsuranceBlip. Her work explains costly decisions like minimum versus full coverage and term versus whole life, helping readers choose coverage based on their situation rather than guesswork.
Minimum coverage can leave drivers financially exposed.
Potential risks include:
Damage to your own vehicle
Theft
Weather damage
Vandalism
Hit-and-run damage
Understanding these risks helps drivers decide if lower premiums are worth reduced protection.
Choosing the Right Coverage Depends on Risk and Budget
Choosing between minimum and full coverage depends on balancing affordability and financial protection. While minimum coverage lowers premiums, full coverage reduces financial exposure.
Understanding your vehicle value, risk tolerance, and financial situation can help you make a smarter insurance decision.
Some drivers move from full coverage to minimum coverage when:
Vehicle value declines
Loan is paid off
Repair costs exceed vehicle value
They build emergency savings
Rule of thumb: If your annual premium exceeds about 10% of the vehicle value, it may be worth reevaluating coverage.
How to Decide Between Minimum and Full Coverage
Drivers can consider these questions:
What is my vehicle worth?
Could I afford to repair or replace it?
How much financial risk am I comfortable with?
How large is the premium difference?
Do I live in a high-risk area?
Balancing cost and protection helps drivers choose appropriate coverage.
Frequently Asked Questions
Is full coverage required by law?
No. Only minimum liability coverage is typically required. Full coverage is optional unless required by a lender.
Is full coverage worth it for older cars?
It depends on the vehicle value. If repair costs would exceed the vehicle value, minimum coverage may make more sense.
Can I switch from full coverage to minimum?
Yes. Drivers can usually adjust coverage at policy renewal or by contacting their insurer.
What does full coverage not include?
Full coverage usually does not include maintenance, mechanical failure, or normal wear and tear.
Not Sure Which Coverage Level Fits Your Budget?
By learning how factors like age, coverage, and vehicle type affect premiums, drivers can better control their insurance expenses. Using tools like cost estimators can help you balance affordability and protection.
Quickly estimate costs for medical emergencies, cancellations, and lost luggage based on your destination and duration. Get the coverage you need to travel with total peace of mind.
Find out exactly how much coverage your family needs to stay protected. This tool analyzes your debts, income, &future goals to provide a personalized insurance target in minutes.
Protect your biggest investment without overpaying. Estimate your annual premiums based on home’s value, location & safety features to find a policy that fits your budget.
Get a clear picture of your potential healthcare costs. Use this estimator to compare plan types & see how different deductibles & coverage levels impact your monthly premium.
Secure your company's future with the right coverage. Quickly calculate estimated costs for general liability, property, and worker’s compensation based on your industry and team size.