Menu
Auto insurance premiums are not random. Insurance companies calculate rates based on risk factors that help predict the likelihood of claims.
Understanding what affects auto insurance costs can help drivers make smarter decisions and potentially lower their premiums over time.
If you want to estimate how these factors affect pricing, you can also use our Auto Insurance Cost Calculator to see how coverage choices influence insurance costs.
Use our free calculator to estimate potential costs based on age, vehicle type, and coverage level.
Table of Contents
Insurance companies use risk models to estimate how likely a driver is to file a claim. These models consider multiple personal and vehicle-related factors.
Some factors increase risk, while others may reduce it.
Each insurer weighs these factors differently, which is why quotes can vary.
Age is one of the strongest pricing factors. Younger drivers typically pay higher premiums because statistics show they are involved in more accidents.
Typical trend:
Experience often matters as much as age.
A clean driving record usually results in lower premiums.
Insurance companies may increase rates after:
Drivers with multiple violations may be considered high-risk.
The car you drive significantly affects insurance pricing.
Insurance companies consider:
Typical pricing patterns:
Location affects insurance because risk varies by area.
Insurance companies may consider:
Urban areas often have higher premiums than rural areas.
The more protection you choose, the more insurance typically costs.
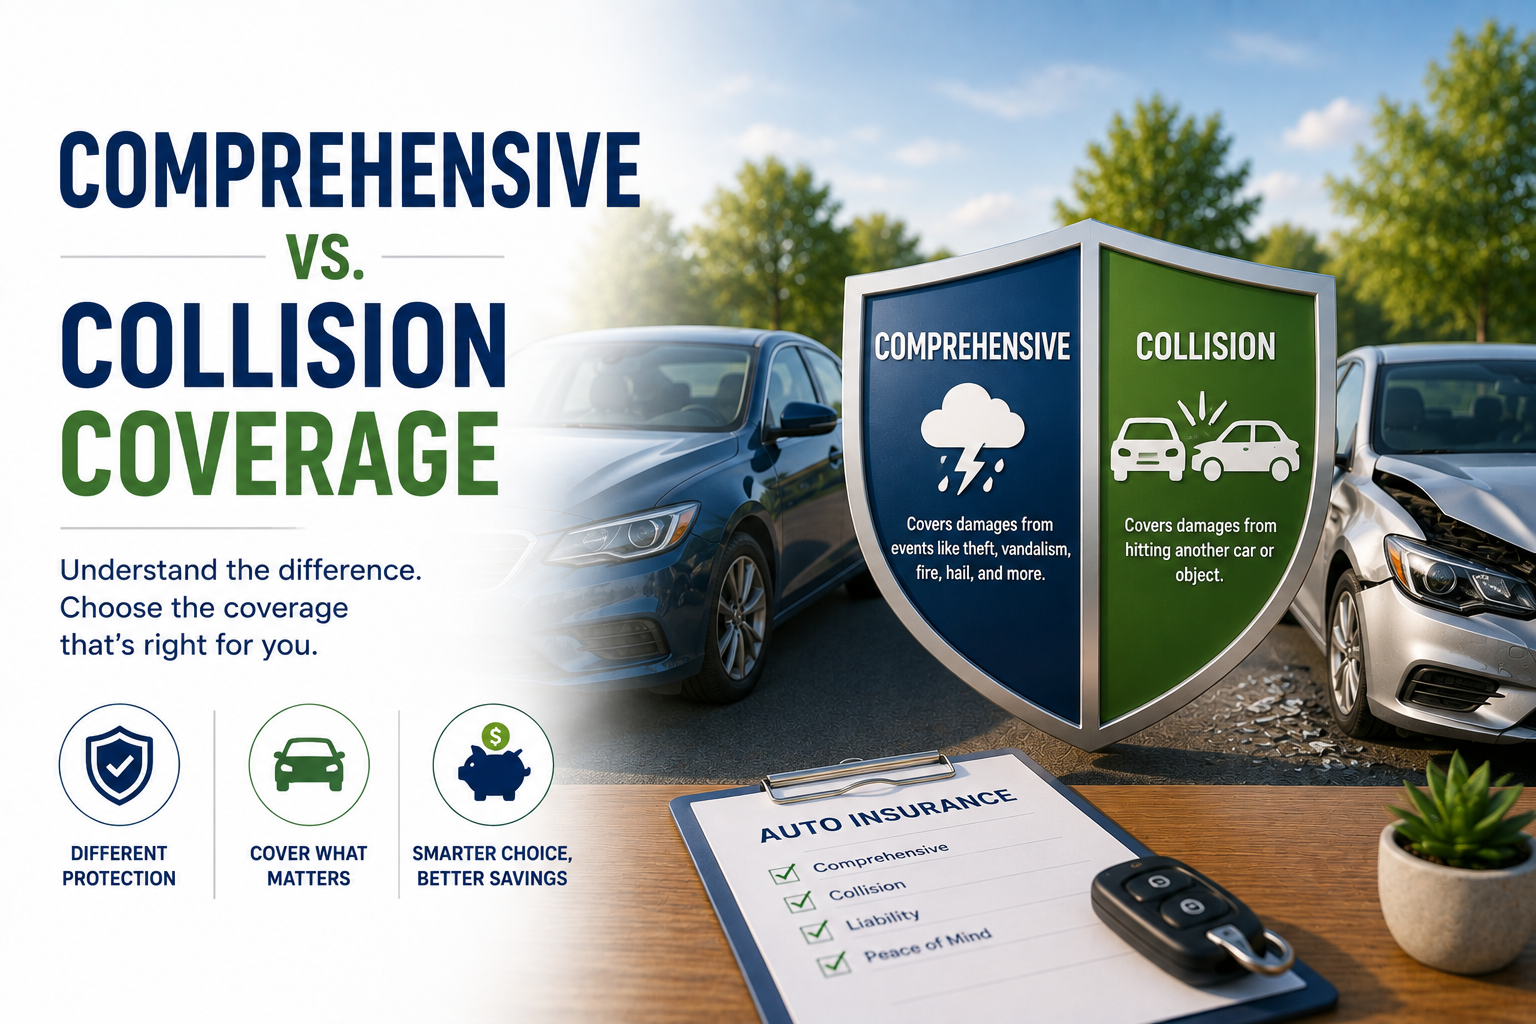
Minimum coverage usually costs less but provides limited protection. Full coverage costs more because it protects your vehicle as well.
Learn more in our guide on Minimum vs Full Coverage Auto Insurance.
Your deductible affects how much you pay monthly.
Many drivers choose deductibles based on savings and risk tolerance.
Drivers who spend more time on the road typically face higher risk exposure.
Insurance companies may ask:
Lower mileage sometimes qualifies for lower premiums.
Previous claims may increase premiums.
Insurance companies may review:
Frequent claims may indicate higher future risk.
In some states, insurers use credit-based insurance scores as a pricing factor. These scores are not traditional credit scores but are used to estimate risk patterns.
Some states restrict or prohibit this practice.
Insurance pricing is rarely based on a single factor.
Insurance companies evaluate overall risk profiles rather than individual factors alone. This explains why quotes can vary significantly.
Because insurance pricing varies widely, calculators can help you estimate realistic costs based on age, vehicle type, coverage level, driving record, and location.
Some pricing factors cannot be changed, such as age or location. However, drivers can influence:
Focusing on controllable factors can help reduce premiums over time.
Drivers sometimes reduce premiums by:
Small adjustments may produce meaningful savings.
You may also find these tools helpful:
Auto insurance rates reflect a combination of driver, vehicle, location, and policy choices. Although you cannot change every input, maintaining a clean driving record, reviewing your coverage, and comparing quotes can help you manage costs.
Use our Auto Insurance Cost Calculator to see how different driver and coverage details may affect your estimated premium.
© 2026 InsuranceBlip. All rights reserved. Website created & managed by Infolytics.