ACA Subsidy Calculator

See What Premium Assistance You Actually Qualify For

What Is an ACA Subsidy Calculator?

An ACA subsidy calculator estimates how much premium assistance you may qualify for on a marketplace health insurance plan, based on your household income, household size, and location. For many marketplace shoppers, the subsidy meaningfully changes the actual monthly cost compared to the full sticker price discussed in how much does health insurance cost, which is why checking subsidy eligibility before comparing plans is one of the most impactful steps in the entire process.

The subsidy, formally called the premium tax credit, is designed to cap what a household is expected to pay toward a benchmark health plan at a percentage of their income, with the government covering the remainder up to that benchmark cost.

How ACA Subsidies Are Calculated

Your subsidy amount is based on your household income as a percentage of the federal poverty line, adjusted for household size, compared against the cost of the second-lowest-cost Silver plan available in your area, commonly called the benchmark plan. The government calculates what percentage of your income you would be expected to contribute toward that benchmark plan, and the subsidy covers the difference between that expected contribution and the benchmark plan's actual premium.

This structure means your subsidy amount is tied specifically to the benchmark Silver plan's cost in your area, not to whichever plan you actually choose. If you select a plan that costs more than the benchmark, you pay the difference yourself. If you choose a plan that costs less, such as a Bronze plan, the same subsidy amount can significantly reduce or in some cases fully cover that lower premium.

Check Your Subsidy Eligibility

See how much premium assistance you likely qualify for based on your household income and size.

Kevin Brooks
Insurance Research Analyst
Kevin Brooks covers insurance pricing and cost research at InsuranceBlip. His work analyzes the rating factors insurers use, including driving history, location, credit score, and vehicle type, helping readers understand why they pay what they pay and how to pay less.
Subsidy Eligibility by Income Level

Income as % of Federal Poverty Line Expected Contribution Toward Benchmark Plan Typical Subsidy Impact
Up to 150% 0% Benchmark Silver plan often available at no premium cost
150% – 200% 0% – 2% Substantial subsidy, benchmark plan remains low cost
200% – 300% 2% – 6% Meaningful subsidy, noticeable reduction from full premium
300% – 400% 6% – 8.5% Smaller subsidy, still reduces cost versus full premium
Above 400% 8.5% (capped) Subsidy available if benchmark plan would otherwise exceed 8.5% of income

The removal of the traditional four hundred percent income cliff means households above that threshold can still qualify for a subsidy if the benchmark plan would otherwise cost more than eight and a half percent of their income, a meaningful change from how the program originally worked when it first launched.

How to Use Your Subsidy

Most marketplace enrollees apply their subsidy as an advance premium tax credit, meaning the government pays the subsidy amount directly to the insurer each month, and you only pay the remaining portion of the premium yourself. Alternatively, you can choose to pay the full premium each month and claim the entire subsidy as a credit when filing your taxes, though most enrollees prefer the advance option since it reduces the monthly cost immediately rather than waiting until tax season.

Choosing which plan tier to apply your subsidy toward is a separate decision from the subsidy calculation itself, since the subsidy amount stays fixed based on the benchmark Silver plan regardless of which tier you ultimately select. See Bronze vs Silver vs Gold vs Platinum plans compared for how to think through that separate decision once you know your subsidy amount.

How an ACA Subsidy Lowers Your Premium

Common Scenarios

Browse Insurance Guides

Insurance Basics Guides
Insurance Cost Guides
Insurance Comparison Guides
Insurance Coverage Guides

Insights From Recent Articles

HMO vs PPO Healthcare Guide
HMO vs PPO: What's the Difference?
Workers Comp Insurance Cost Guide
Workers Comp Insurance Cost: The Full Breakdown
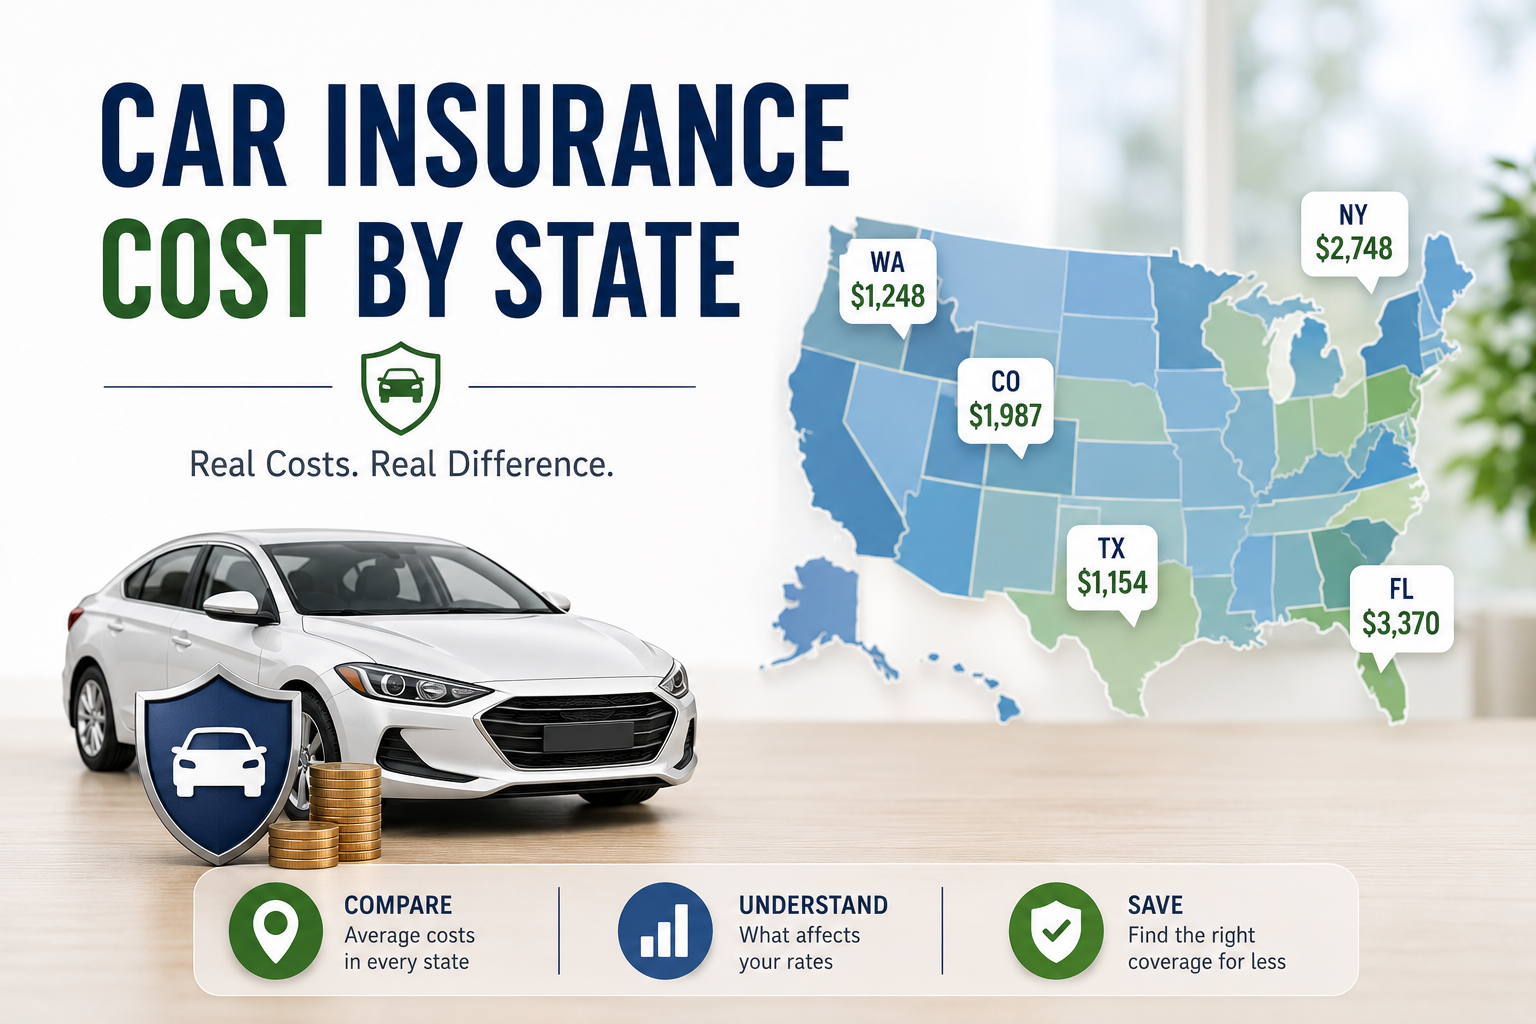
Car Insurance Costs by State
Car Insurance Cost by State
Does Credit Score Affect Your Car Insurance Rate
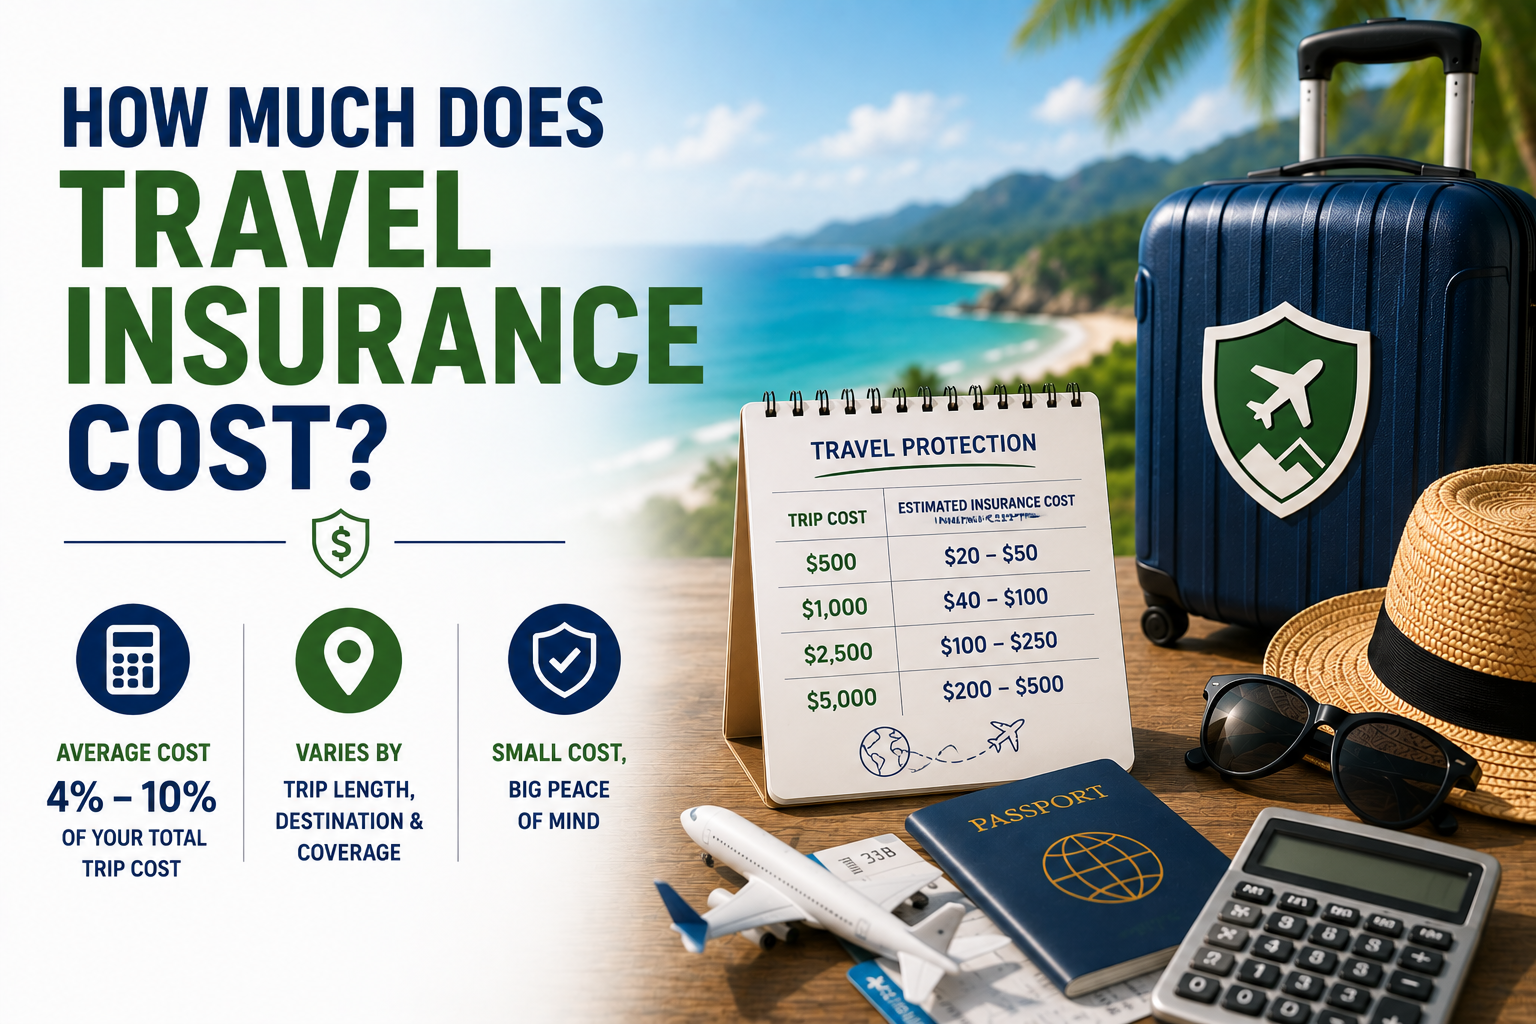
How Much Does Travel Insurance Cost

Explore By Insurance Types

Auto Insurance
Business Insurance
Health Insurance
Home Insurance
Life Insurance
Travel Insurance

Frequently Asked Questions

Do I have to pay back my subsidy?

Potentially, yes, if your actual income for the year ends up higher than what you estimated when enrolling. Since the advance premium tax credit is based on an income estimate, a significant income increase during the year can mean you received more subsidy than you were ultimately entitled to, which gets reconciled when you file taxes and may require repaying some or all of the difference.

What if my income changes during the year?

Reporting an income change to the marketplace as soon as it happens allows your subsidy amount to be adjusted going forward, reducing the risk of a large reconciliation bill at tax time. Waiting until tax season to report a significant income change that occurred months earlier is one of the more common reasons enrollees are surprised by an unexpected repayment.

Can I get a subsidy if my employer offers insurance?

Generally, no, if your employer’s coverage is considered affordable and meets minimum value standards under ACA rules. If employer coverage is offered but considered unaffordable, defined as costing more than a specific percentage of your income, you may still qualify for a marketplace subsidy instead of using the employer plan.

Check This Before Comparing Any Plan

An ACA subsidy can change the real cost of coverage dramatically compared to the sticker price on a plan listing, which is exactly why estimating it should happen before you start comparing specific plans, not after. Understanding that your subsidy is tied to the benchmark Silver plan, not whichever tier you ultimately choose, also helps explain why the same subsidy can look very different in practice depending on which plan you apply it toward. Visit our Health Insurance hub for the fuller picture of choosing a plan once you know your subsidy.

Trusted Insurance Resources

Estimate Your Own Subsidy

See your estimated premium assistance based on your household income and size.

Try Health Insurance CalculatorExplore Insurance Guides

At A Galance

Insurance Tools & Estimators

Use our free tools to estimate insurance costs before you shop. No personal information required just straight forward estimates.

Auto Insurance Calculator

Estimate your car insurance costs based on your age range, driving history, vehicle type, coverage level, & location. Understand how each factor affects your premium.

Life Insurance Needs Calculator

Calculate how much life insurance coverage your family might need based on your income, debts, and financial goals.

Health Insurance Estimator

Understand how premiums, deductible, out-of-pocket costs vary across different plans. Useful for comparing coverage options during enrollment or life change.

Business Insurance Estimator

Estimate general liability and small business insurance costs based on your industry, business size, and coverage needs.

Homeowners Insurance Calculator

Estimate how much homeowners insurance might cost based on your property value, location, and coverage needs.

Travel Insurance Calculator

Estimate trip protection costs based on your destination, trip duration, and the type of coverage you need.