Estimate your monthly health insurance costs based on age, household size, income, and coverage level. No personal information required.
Estimate your monthly health insurance cost using common pricing factors. No signup or personal contact information required.
This health insurance calculator provides a personalised estimate of your monthly premium based on the same core factors that ACA marketplace insurers use to price individual and family plans. Enter your age range, state, coverage tier, household size, income, and tobacco status — and the calculator returns a realistic cost range in seconds.
Health insurance premiums are calculated using actuarial models that weigh individual risk factors against average claim costs in your area. Our calculator uses these same widely known inputs — age, location, plan tier, tobacco use, income, and family size — to generate a realistic cost range based on 2026 ACA marketplace benchmark data published by the Centers for Medicare & Medicaid Services (CMS).
The figures shown are estimates rather than exact quotes. Actual premiums depend on the specific plan you choose, your insurer, and any subsidies you qualify for based on your household income. The goal of this tool is to help you understand what health insurance is likely to cost before you begin comparing real plans — so you can budget accurately and make informed decisions.
This calculator does not require personal information and does not generate quotes from insurance companies. It is an educational planning tool.
Several key factors determine your health insurance premium. Under ACA rules, insurers are limited to using only these factors — they cannot charge more based on health history or pre-existing conditions.
Age is the single biggest factor in health insurance pricing. Under ACA rules, a 60-year-old can be charged up to 3 times what a 21-year-old pays for the same plan. Premiums rise steadily from age 21 and increase more sharply after age 50.
Premiums increase for each additional person covered under your plan. Family plans include a combined deductible and a higher out-of-pocket maximum. In 2026, the ACA family out-of-pocket maximum is $18,900 — nearly double the individual cap of $9,450.
Premiums vary significantly by state and even by county. Insurers set rates based on local medical costs, hospital pricing, the number of insurers competing in your area, and state-level insurance regulations. The same Silver plan can cost $300/month in one state and $600/month in another.
Under ACA rules, insurers can charge tobacco users up to 50% more than non-tobacco users for the same plan. This surcharge applies in most states California, Massachusetts, New Jersey, New York, Rhode Island, Vermont, and Washington D.C. prohibit tobacco rating entirely. Quitting tobacco is one of the most significant ways to reduce your health insurance premium.
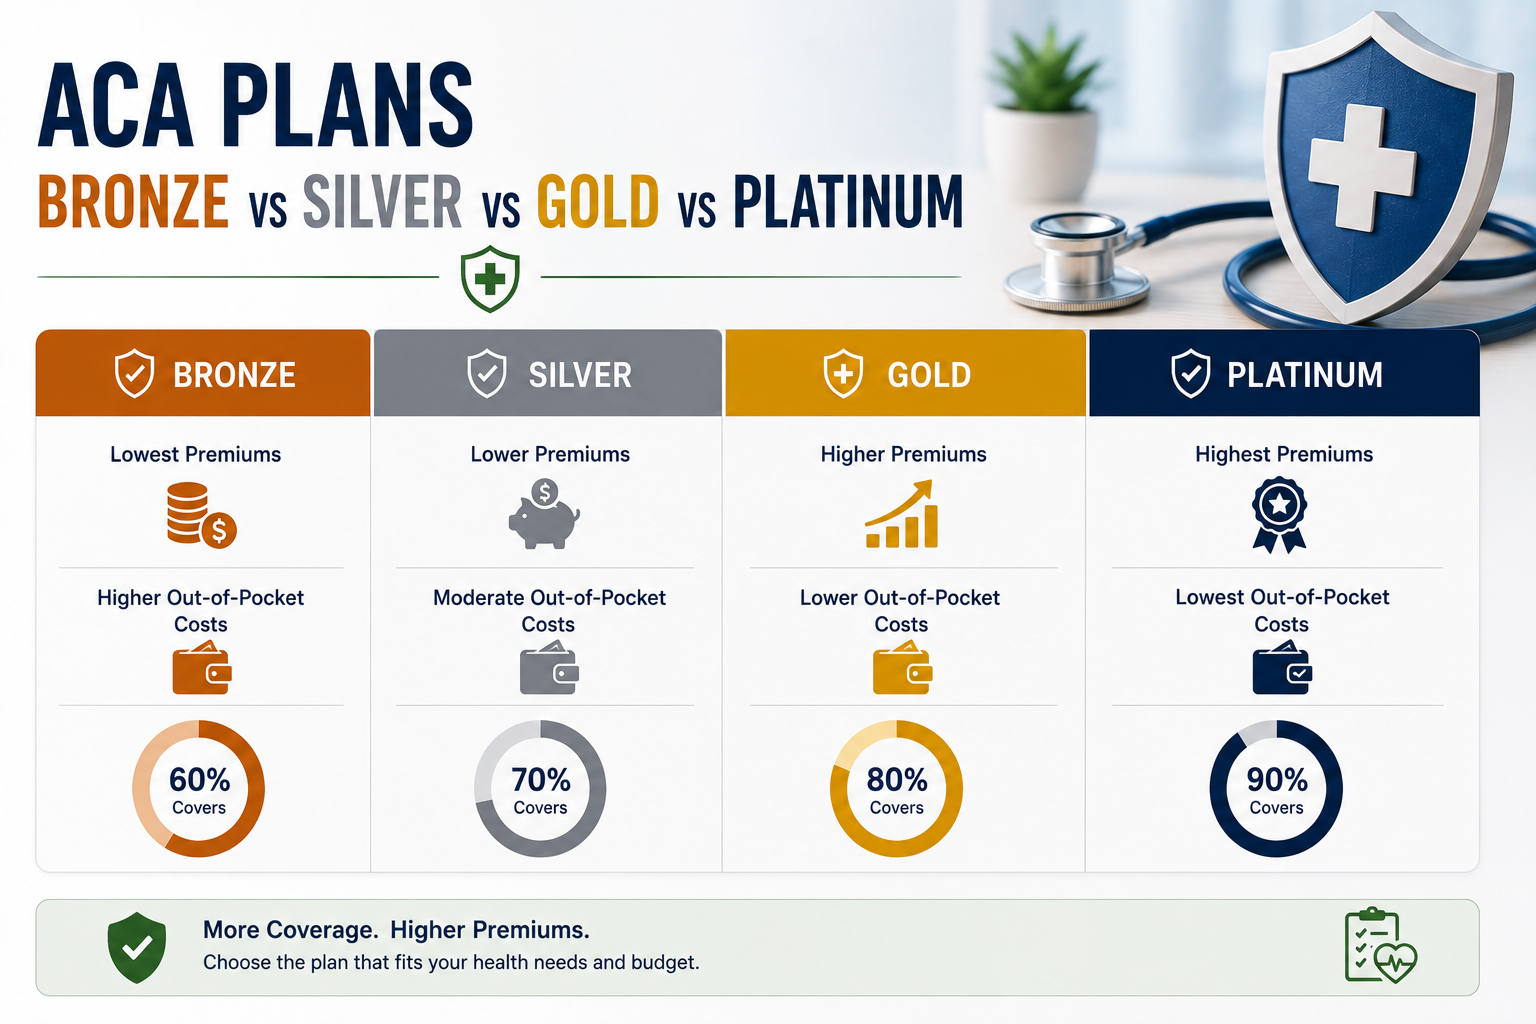
ACA plans come in four tiers — Bronze, Silver, Gold, and Platinum. Bronze plans have the lowest monthly premium but the highest deductible. Platinum plans have the highest premium but the lowest out-of-pocket costs. The tier you choose directly sets your monthly cost and how much you pay when you actually use care.
Health insurance premiums vary between insurers even for identical coverage in the same location. Two people with the same age, income, and plan tier can receive different quotes depending on which insurer they choose — because each company uses its own pricing model and has different claims experience in your area.
For this reason, the calculator provides a cost range rather than a single number. The range reflects typical premium variation between competing insurers offering the same tier in your selected state. In markets with more insurer competition, the range is narrower. In markets with fewer insurers, premiums tend to cluster higher.
This estimate should be used as an educational reference point — not as a final number. Use it to set your budget and understand how different inputs (tier, age, income) affect cost. Then use healthcare.gov or your state’s marketplace to compare actual plans available to you during open enrollment.
A health insurance cost estimator is most valuable in these situations:
Using a cost calculator before requesting real quotes helps you narrow your options, understand the trade-offs between premium and deductible, and avoid enrolling in a plan that does not fit your actual budget or health needs.
Related Tools
Explore some of our featured tools related to health insurance
Find the right deductible level based on your expected healthcare usage and savings. Understand how raising your deductible affects your monthly premium.
Compare HMO, PPO, and EPO plans side by side on cost, coverage, and flexibility — so you can choose the right plan type for your situation.
Find out if your household income qualifies you for ACA premium tax credits. Enter your income and household size to check your eligibility instantly.
Health Insurance Special
Many people pay significantly less than the estimates shown above because they qualify for ACA premium tax credits — subsidies that reduce your monthly premium directly. In 2026, households earning between 100% and 400% of the federal poverty level (FPL) are eligible, and expanded rules introduced in 2021 extend some subsidy eligibility above 400% FPL.
Subsidy reference table:
| Household Size | 100% FPL | 200% FPL | 300% FPL | 400% FPL |
|---|---|---|---|---|
| 1 person | ~$15,060 | ~$30,120 | ~$45,180 | ~$60,240 |
| 2 people | ~$20,440 | ~$40,880 | ~$61,320 | ~$81,760 |
| 4 people | ~$31,200 | ~$62,400 | ~$93,600 | ~$124,800 |
Subsidy amounts vary by income, household size, state, and benchmark Silver plan cost in your area. The income field in our calculator provides a subsidy eligibility indicator based on these thresholds.
If you selected an income range in the calculator and your estimate showed a subsidy note — use healthcare.gov to confirm your exact tax credit amount and see plans with subsidies applied.
This calculator provides an estimate based on 2026 ACA marketplace benchmark data published by CMS and the Kaiser Family Foundation (KFF) methodology. When your inputs are accurate and complete, results typically fall within 10–25% of actual marketplace premiums in your area. It is a planning tool — use real quotes from healthcare.gov or a licensed broker before making a final enrollment decision.
No. This is an educational estimate tool, not a quote engine. A real insurance quote requires an insurer to verify your information and confirm available plans in your specific zip code. Use this calculator to understand your expected cost range and budget — then visit healthcare.gov or your state’s marketplace during open enrollment to compare actual available plans with real premiums applied.
No personal information is required. The calculator uses general inputs — age range, state, coverage tier, household size, income range, and tobacco status — to generate your estimate. No name, email, date of birth, Social Security number, or contact information is collected or required.
Each insurer files its own premium rates with state regulators based on its claims experience, administrative costs, and projected medical spending in your area. Even for the same plan tier in the same zip code, different insurers may price a Silver plan $50–$150/month apart. This is why comparing multiple plans during open enrollment — rather than choosing the first result — consistently leads to better value.
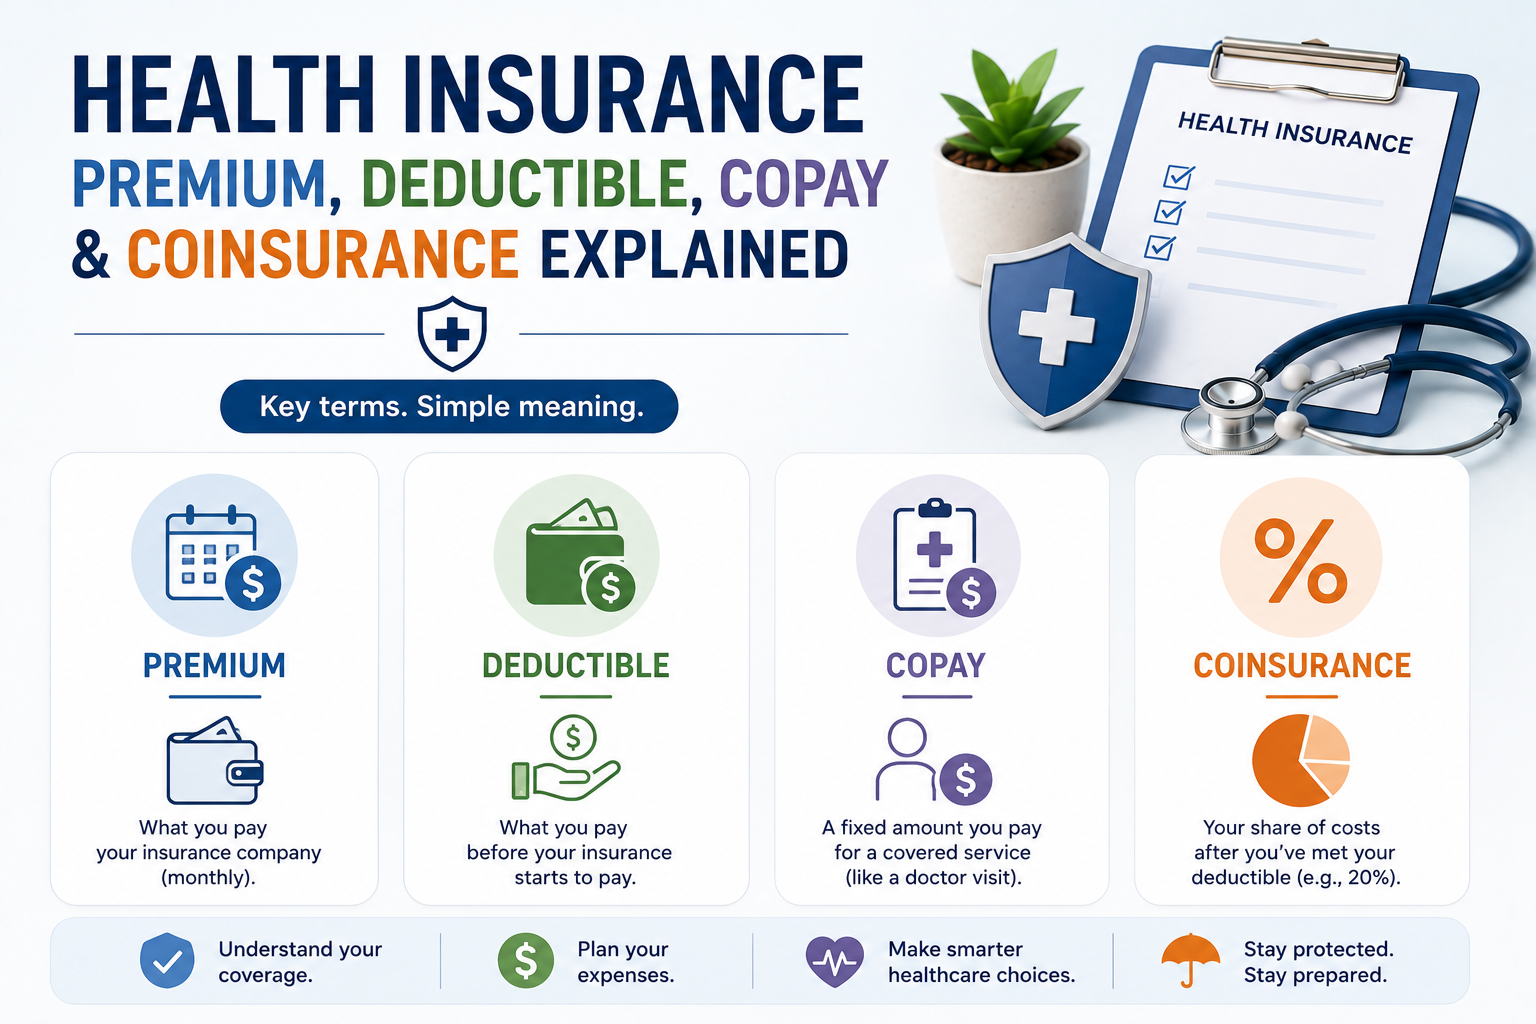
Your premium is the fixed monthly amount you pay to maintain health insurance coverage — regardless of whether you use any medical care that month. Your deductible is the amount you pay out of pocket for covered medical services each year before your insurer starts sharing costs. A Bronze plan has a low premium but a high deductible (often $6,000–$7,000). A Gold plan has a higher premium but a low deductible (often $1,000–$2,000). The right balance depends on how much healthcare you expect to use.
ACA premium tax credits reduce your monthly health insurance cost if your household income falls between 100% and 400% of the federal poverty level (with expanded eligibility above 400% FPL under current rules). The credit is applied directly to your monthly premium — reducing what you pay out of pocket each month. Our calculator flags subsidy eligibility based on the income range you enter. Visit healthcare.gov to see your exact credit amount.
Related Guides
Looking for more in-depth answers? Explore our latest health insurance guides covering costs, coverage options, policy comparisons, and expert tips.

You may also find these tools helpful:
© 2026 InsuranceBlip. All rights reserved. Website created & managed by Infolytics.